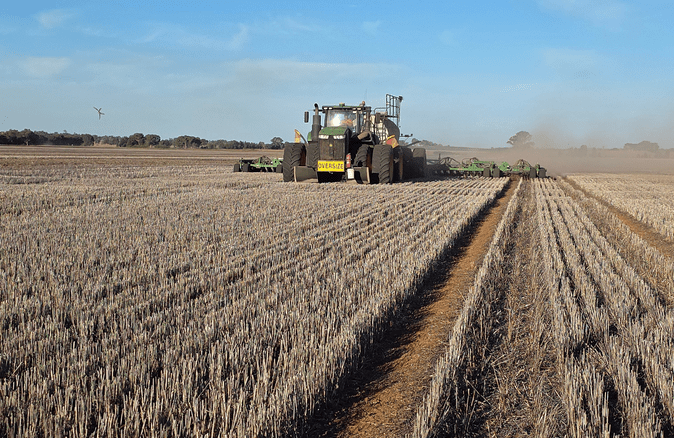
Sowing canola into wheat stubble at Grenfell in NSW on April 23. Photo: Broden Holland
AUSTRALIA is set to plant a reduced winter crop this year, as the nation’s grain growers contend with mixed weather conditions and the impacts of significantly-higher farm input costs, Rabobank says in its 2026-27 Australian Winter Crop Forecast.
The specialist agribusiness bank estimates Australia’s winter cropping area will come in at 23.1 million hectares (Mha) for the season, down 8 percent on last year, and 4.3pc below the five-year average.
The decline in cropping area is forecast to come at the expense of wheat, with the nation’s wheat planting estimated to be down by a substantial 20.4pc on last year to 9.8Mha, and 24pc below the five-year average, according to the annual outlook from the bank’s RaboResearch division.
Barley, canola and pulse plantings are forecast to increase on last year’s area, with these commodities offering growers potentially stronger margins than wheat, according to report author RaboResearch senior grains and oilseeds analyst Vitor Pistoia.
By state, while planted area is projected to be up by 5.7pc in Western Australia to a record 9.47Mha, Queensland’s crop is estimated to be 34.8pc lower at 1.06Mha, and New South Wales down by 29.2pc to 4.82Mha.
Planted area in South Australia and Victoria is forecast to remain relatively stable at 3.99Mha, up 0.3pc, and 3.74Mha, up 0.9pc, respectively.
Mr Pistoia said this disparity reflected the dry conditions that had been experienced across Qld and northern NSW this year, alongside better seasonal starts in WA and SA.
Uneven start
Mr Pistoia said Australia has entered the 2026-27 winter-cropping season with a more uneven and weather-dependent cropping area than in recent years.
RaboResearch analyst Vitor Pistoia.
“The season is opening with a clear geographic split across Australia’s cropping regions,” Mr Pistoia said.
“Conditions on the northern east coast, particularly in southern Qld and northern NSW, have been dry through summer and early autumn, leaving limited topsoil moisture and delaying sowing.”
In contrast, Mr Pistoia said WA, SA, Vic, and southern NSW had entered the season with average to above-average soil moisture, allowing earlier seeding, including for canola in WA and SA, which was sown as early as late March.
“This marks a reversal from the past two seasons, when eastern regions of Australia held stronger soil moisture at this time and other parts of the country were waiting for the season to break.
“Recent rainfall which has fallen across some cropping regions in Qld and NSW this month, while beneficial, will not be enough to support a full cropping program, as some regions require up to 100mm of rainfall to replenish soil moisture.”
Looking at the winter-cropping season ahead, Mr Pistoia said there appeared to be a likelihood of “lower growing-season rainfall”, with the high risk of a shift towards El Niño conditions during the winter months and low probability of above-average rainfall across the Australian wheatbelt.
“This means starting-season soil-moisture levels are expected to play a key role in determining yields this season, contributing to greater variability across the cropping belt.”
And with above-average temperatures forecast across many cropping regions for the period, warmer minimums may reduce frost risk, although higher daytime temperatures are likely to increase moisture demand, Mr Pistoia said.
Elevated input costs
The report said elevated farm input costs – particularly higher global fertiliser and diesel prices due to the Middle East conflict – were increasing production costs for Australian growers and influencing cropping decisions this quarter.
“These higher costs are encouraging shifts towards lower-input crops and contributing to a reduction in total cropping area.”
While higher input costs are likely to contribute to lower grain production this year, the elevated price of diesel fuel may also reduce the amount of global grain on export markets, he said, with some regions potentially choosing to supply their local market rather than sending it for export.
“This may potentially slow global grain movements later in the season to ports, providing some underlying support to international grain prices.”
Commodities
RaboResearch expects Australia’s grain growers to plant 5.1Mha of barley this year, up 4.1pc on last year and 14.6pc above the five-year average.
Mr Pistoia says barley markets remain supported by resilient feed demand, both domestically and across key export markets in Asia and the Middle East.
“While global barley stocks remain comfortable following strong 2025 production, tightening supply prospects and steady livestock demand are expected to provide a price floor.”
Area planted to canola this year is projected to be up 8.5pc on last season to 3.7Mha, 7.6pc above the five-year average.
The broader oilseed market globally is supported by strong demand linked to biofuel policies and elevated energy prices, which is keeping canola stocks in check, RaboResearch said.
The expected expansion in canola cropping area in Australia reflected “improved relative returns compared with wheat” as well as favourable early-season moisture, particularly in WA and SA, Mr Pistoia said.
“While this additional supply may temper local price upside at harvest, canola continues to benefit from rising global energy prices and biofuel mandates.”
Australian growers are forecast to plant approximately 3.5Mha of area to pulses this season, including chickpeas, lentils, lupins, peas and faba beans.
This is up by 0.7pc on last year, and 42.3pc above the five-year average.
Mr Pistoia said India remained the key “swing factor” in global pulse markets, with expectations of higher Indian import duties, which had been priced into markets in late 2025, yet to materialise.
Global pulse area was likely to expand this season, he said, although at a slower pace than last year.
“A developing El Niño raises the likelihood of lower yields both here on Australia’s east coast, but also in South Asia,” Mr Pistoia said.
“As a result, we expect prices to remain range-bound, as renewed demand faces headwinds from weaker currencies in key importing countries and higher freight costs, reducing importers’ purchasing power.”
On wheat, the RaboResearch report said new pricing dynamics were emerging as production is about to drop in Australia and globally.
“The global wheat market is shifting from a well-supplied 2025 to a more constrained balance in 2026, driven by higher input costs, weaker profitability and emerging weather risks,” Mr Pistoia said.
Production and export outlook
In terms of production from the 2026-27 winter cropping season, Rabobank’s current base case forecast is for approximately 21.3 million tonnes (Mt) of wheat to be heading for the bins at harvest.
This would be down 41pc on the 35.8Mt of wheat produced in the last crop.
For barley, the current projection is for a harvest of 14.1Mt, still 15pc down on last season’s 16.7Mt, despite the increased area planted.
Mr Pistoia said this is due to expected lower yields as a result of dry conditions over NSW and Qld, lower nitrogen applications rates and the El Niño outlook.
Canola production is projected to reach 6.4Mt, down 13pc on last season’s 7.4Mt, but in line with the five-year average.
Despite a larger area to be planted to canola this year, the lower production outlook is driven by the increased likelihood of dry weather conditions over the pod-filling period due to the prospects of El Niño, Mr Pistoia said.
The report says Australian exports for the 2025-26 season to date are broadly on track to avoid a significant carryover of grain and oilseeds stocks building up for the season ahead.
For the first half of the marketing year ending September 30, wheat shipments had reached 12.6Mt, in line with the pace to meet the full-year export program.
Barley exports had been strong at 6.4Mt, largely driven by demand from China. In contrast, canola exports for the period were approximately 300,000t under recent years’ average, reflecting a recovery in European stocks and weaker import demand.
Looking ahead, alongside policy developments, rising fuel costs are likely to become an increasingly important driver in the global trade outlook, the report said.
“This is expected to favour Australian exports into South East Asia, where shorter shipping distances improve competitiveness relative to the Americas.”
Source: RaboBank
HAVE YOUR SAY