 Weather: Central Brazil remains the key watch. October rainfall has been sparse, Mato Grosso soy planting was 33 percent done at October 9 and running ahead of average, and temperatures near 40 degrees Celsius stress young plants when rain fails, with this season’s El Niño already the strongest on record in the Pacific.
South-east Asian drought is now a physical supply issue as well as a yield story. MPOC says El Niño output impacts typically lag 9-12 months, with Malaysian production falling 13pc or 2.6 million tonnes (Mt) after the 2015 “super” El Niño, and Indonesia’s Sumatra and Kalimantan turning drier since late June. MBSB sees the peak most likely between November and January.
Black Sea and US Plains winter sowing is lagging. Russia’s Agriculture Ministry trimmed its winter sowing plan to 19M hectares from 20M amid sharply higher input costs, with sowing behind last year’s pace, and it has reached 70pc of plan with a record 95Mt of wheat harvested. US winter wheat planting sits at 63pc against a 69pc average, while open US harvest weather is weighing on corn and beans.
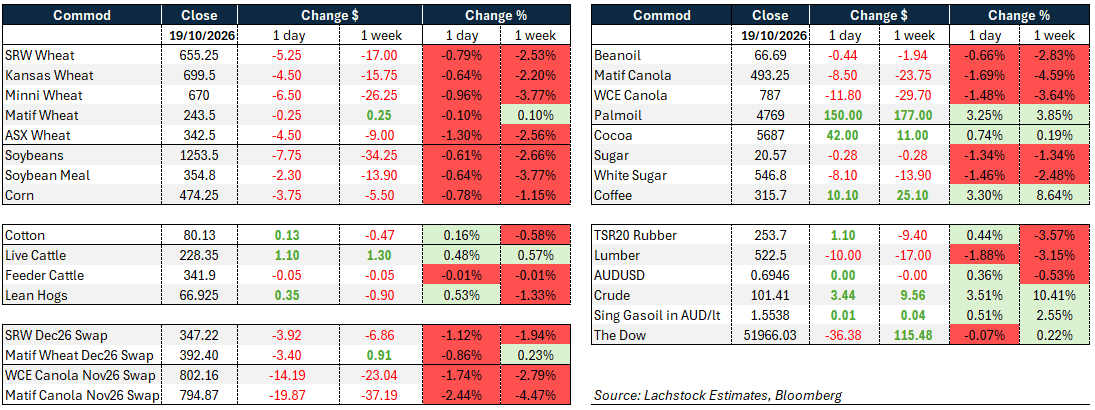
Markets: Wheat’s seven-week slide continued. Minni lost 3.77pc and SRW 2.53pc on the week, and ASX fell 1.3pc to A$342.5/t overnight. The collapse in Russian October exports to 2Mt has yet to translate into a bid while importers stay hand to mouth.
Corn broke technical support at US$4.70 per bushel on the largest fund long liquidation in the COT report, around 63,000 contracts. A weak 672,000t inspection figure and a big harvest point to further downside until Ukrainian availability becomes clearer.
Oilseeds split on logistics. MATIF canola fell 4.59pc and WCE 3.64pc on the week, tracking soyoil weakness and farmer selling. Palm rallied 3.85pc as Indonesia’s river drought stranded supply, despite Malaysia’s inventory glut.
Energy remains the dominant macro driver. Crude rose 10.41pc on the week, Brent sits near $110 on Hormuz risk and diesel is at a premium. AUD-USD is steady at 0.6946c but down 0.53pc on the week, as sovereign debt, fiscal and midterm risks keep inflation and rate pressure elevated.
Day ahead – Australia: The rain in the north has moved from being positive for the feedgrain balance sheet to deeply concerning for cereal quality. We have at least two weeks of predicted rain, with most regions through the downs into northern New South Wales looking at a minimum of 100mm.
Southern early harvest has been super mixed quality – BarX specs are circulating widely – 100pc below the screen!
BOM is catching some more heat – reports that they have cut and paste from one year to the other adds to the pile on. This feels like a messy harvest already.
Wheat: Wheat opened the week where it left off, extending a seven-week losing streak that Price Futures Group’s Austin Schroeder says has made it the leader to the downside. Fears over the historically small US crop have faded as the new winter crop goes in. Without support from MATIF or corn, the market drifted with the flow.
Winter wheat spreads were mostly lower and the Minny curve was flat. The SRW Dec26 swap fell 3.92 to 347.22 (-1.12%), and the MATIF Dec26 swap fell 3.40 to 392.40 (-0.86pc), although it is still up 0.91 on the week.
US premiums over the rest of the world are narrowing but are not yet competitive. Inspections of 240,000t missed the 350,000t estimate, leaving the export pace down 36pc year on year, with Vietnam the top destination.
Funds cut wheat longs by around 9000-10,000 contracts in the week to October 13.
After the close, winter wheat planting reached 63pc, against 64pc expected, 51pc last week and a 69pc five-year average.
The Black Sea remains noisy, but the market is comfortably numb to it. Putin has proposed a summit next month with Trump and Xi to negotiate an end to the war on terms favouring Moscow, which Ukrainian Foreign Minister Sybiha says would only encourage Putin to prolong it. Ukraine is in talks with Turkiye, Egypt and India on a Black Sea civil navigation corridor for ag exports. Zelenskyy has also asked Poland, Romania, Slovakia and Hungary to allow transit of Ukrainian grain. Romanian F-16s shot down two drones believed to be turboprop Geran-4s. Ukrainian October 8-14 grain exports rose 29pc to 373,000t, with wheat at 295,500t. Russian cash fell $4 to just under $200. Russia is on pace to export only 2Mt of wheat in October, against 5.5Mt last October and 5.6Mt in October 2024. Moscow has lodged documents seeking Chinese approval for winter wheat and barley from selected regions, and Deputy PM Patrushev flagged further grower support measures, including boosting exports.
European cash markets were described as firm. Importers continue to buy the minimum and wait for logistical clarity, a pattern that cannot hold indefinitely.
Corn and oilseeds: Corn led row-crops lower, with December down 1.6pc to $4.66 3/4. AgResource noted the break below its $4.70 support level opens the door to further downside as harvest pushes ahead in open weather. The market is trading like one that recently found 400M bushels plus of new supply and is harvesting its second-largest crop.
Inspections of 672,000t fell well short of the 1.2Mt expected, putting the pace down 2pc year on year, with Mexico the top destination. US harvest reached 44pc, against 45pc expected and a 52pc average. The PNW is again the cheapest origin landed into Asia, while Argentina is the cheapest FOB overall.
Korea Feed Association bought around 65,000t privately, and Taiwan’s MFIG is tendering for up to 65,000t, closing Wednesday. China’s September corn imports jumped 663.6pc year on year to 430,000t.
Brazil’s summer corn planting is 48pc done against a 51pc average. Argentine farmers have sold a record 105,000t across all grains, 25pc above the five-year average.
The bigger question remains whether, and in what capacity, Ukrainian corn reaches the market.
Soybeans caught the harvest blues, with neither product providing a spark. The USDA confirmed flash sales of 114,000t to China and 261,000t to unknown destinations, extending last week’s run of Chinese business, but it drew no response.
Inspections were strong at 2Mt against 1.4Mt expected, and the pace is up 27pc year on year. Harvest reached 64pc, against 66pc expected and a 65pc average. Funds cut bean longs by 6200 contracts. AgRural put Brazilian planting at 26pc against 24pc a year ago.
The complex is at liquidation risk, with meal more available and Chinese buying within balance sheet parameters. Canola resumed its downturn on weaker comparable oils and farmer selling.
The WCE Nov26 swap fell 14.19 to 802.16, down 1.74pc, and the MATIF canola Nov26 swap fell 19.87 to 794.87, down 2.44pc. Alberta harvest was 74pc complete as of October 13, and Nov/Jan traded 12.50 to 13.70 under.
Palm went the other way. Drought on Indonesia’s Kapuas River has stranded processed oil in full tanks, forcing mills to refuse fresh fruit bunches. Malaysia is weighing export tax waivers to clear a glut, and traders see upside capped by elevated Malaysian stocks.
Local: Through the west of the country, the week started on a softer tone. Canola was back $5 to $855, wheat was steady at $383 and barley was a couple of dollars softer at $322 FIS Albany.
HAVE YOUR SAY