Weather: El Niño is building towards its peak, and NOAA CPC puts a 63 percent chance on a very strong event at its peak from November 2026 to January 2027. The Bureau of Meteorology forecasts a peak El Niño 3.4 index of 3.8 C in December 2026.
In Brazil, soil moisture recovered across the Centre-West and soybean planting sped up, with Mato Grosso passing 60pc of planned area, and planting progress has reached 76.12pc, ahead of 70.73pc at the same time last year. However, LSEG expects widespread rains across South America in the second half of November will slow soybean and corn plantings in Argentina, Paraguay, and Brazil.
The El Niño risk is showing up most clearly in softs. Bloomberg reports El Niño is damaging Ecuador’s cocoa crop, while Vietnam still expects coffee output to rise 5pc. Rabobank flags cocoa, palm oil, sugar, Robusta coffee, and Australian grains among the markets most exposed to adverse weather. In the US, winter wheat conditions improved to 53pc good to excellent.
Markets
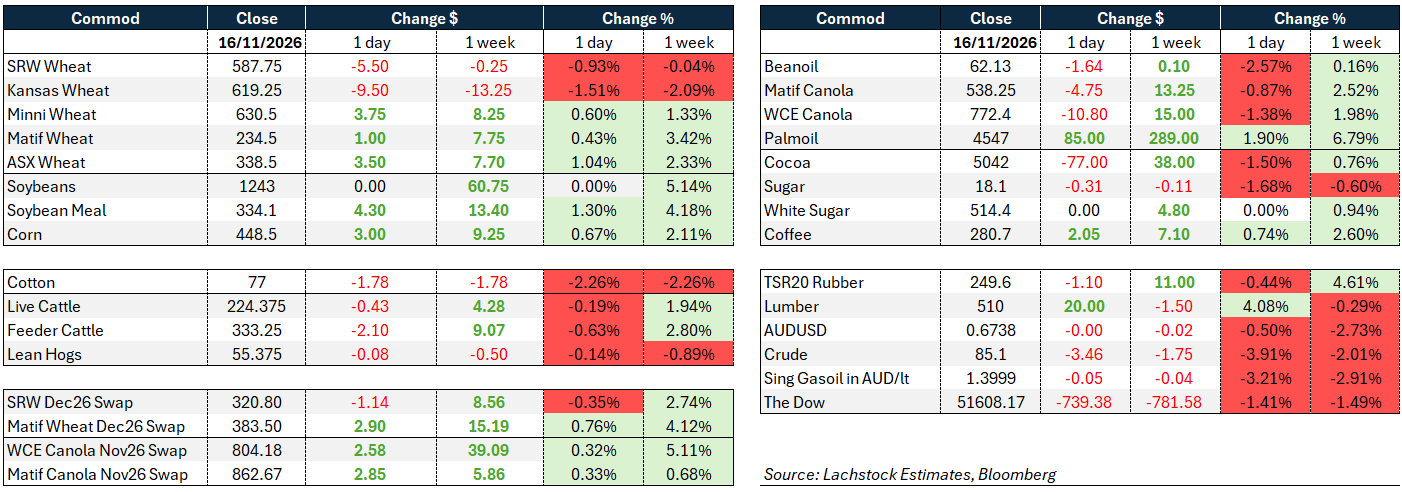
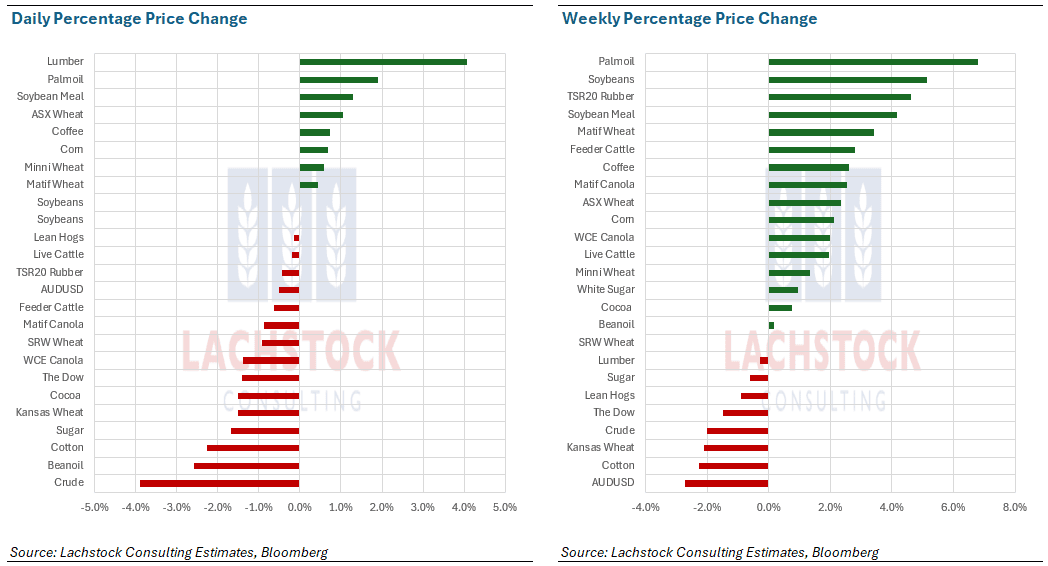
Wheat again traded peace hopes ahead of the APEC trilateral rather than the deterioration in Black Sea logistics, which is getting worse. Kansas led losses on poor demand and better crops, while Minneapolis, Matif and ASX firmed. Funds’ heavy short position leaves room for a sharp short-covering rally if APEC disappoints.
Corn is drawing respect as an export alternative to Ukraine, supported by the Colombian flash sale and Korean buying. Soybeans are on hold until the Trump-Xi meeting, after a record NOPA crush that was bullish for meal and bearish for soyoil.
Vegetable oils took the brunt of crude’s 3.9pc fall. Soyoil dropped 2.6pc, ICE canola 1.4pc and Matif canola 0.9pc, though the Nov26 canola swaps both held small gains.
Risk appetite faded, with the Dow down 1.4pc and crude sharply lower. The AUD’s 2.7pc weekly fall to 0.6738 is supporting Australian prices, with ASX wheat up 3.50 and the Matif Dec26 swap up 2.90 to 383.50.
Day Ahead – Australia
Divergence. Russia and the Ukraine have been talking but, at the same time, they have been bombing – and bombing hard. Ukraine smashed more Russian refining along with a significant Crimean Bridge. So, on the ground, things are getting worse, not better. Yet, markets bleed lower.
Barley has turned favourite for the moment for the exporters which has added some strength in the south ahead of what should be a solid harvest. The exposure to the weather will be significant, especially for Bar1 sales.
Markets should be pretty flat with the AUD doing the heavy lifting right now.
 .
The market sold off on hopes for this week’s APEC summit in Shenzhen, where Trump, Xi and Putin are due to meet on Thursday, even though conditions on the ground worsened.
Ukraine launched its largest drone attack of the war, with Moscow reporting 1,336 drones brought down across 16 regions. The strikes hit the Crimean Bridge, which the Kremlin says is still carrying traffic, and Bunge’s oil plants in Dnipro and Mykolaiv, where one worker was killed.
A Somali-flagged ship carrying wheat from Romania to Egypt also sank off Bulgaria.
Sovecon expects Russia’s November grain exports to fall to 3.15 million tonnes (Mt) from 3.50Mt in October.
Doug Bergman of RCM Alternatives said wheat is trading as if the world has plenty of supply to cover any Black Sea restrictions.
He also noted that funds hold a large short position, which leaves room for a sharp bounce after two months of selling.
Hard Red Winter wheat remains priced too far above the world market. Demand is very thin, acreage is higher and crop conditions keep improving.
Winter wheat rated good to excellent rose to 53pc from 49pc, above the trade estimate of 51pc.
Minneapolis is getting support from quality concerns in Argentina and recent export sales.
Wheat inspections rose to 392,000t from 275,000t the week before.
The SRW Dec26 swap eased 1.14 to 320.80 and the Matif Dec26 swap gained 2.90 to 383.50. ASX wheat rose 3.50 to 338.50, helped by the weaker AUD.
The USDA announced a flash sale of 130,000t to Colombia for 2026-27.
South Korea’s MFG bought up to 136,000t of optional-origin corn and CAPI is tendering for 70,000t.
Inspections were 866,000t, against 908,000t the week before and 2.07Mt a year ago.
Harvest is 88pc done, compared with a 92pc average.
With Ukrainian corn largely absent, buyers will have to lean on the US whenever South America eases off.
For now, a weaker BRL and optimism about the new crop are keeping Brazilian corn competitive.
ADM Investor Services said China buying US corn at the summit would turn sentiment bullish, but Beijing shows no urgency, partly because of the strong dollar.
Soybeans finished unchanged after trading both ways. NOPA reported a record October crush of 234.2m bushels, well above the 223.3m bushel estimate.
Mike Castle of StoneX said the figure helps the catch-up towards USDA’s record 2.78bn bushel crush target.
Meal rose 4.30 to 334.10. Soyoil stocks of 1.171bn lb came in above the 1.135bn lb estimate, and soyoil fell 2.57% to 62.13. Soybean inspections were 1.71Mt, down from 1.91Mt the week before but up on 1.21Mt a year ago.
Brazil rainfall is plentiful, and some traders say it is now too much. Canola fell sharply, dragged down by crude, soyoil, rapeseed and palm.
ICE January lost 10.80 to C$772.40 and is holding above its 200-day moving average by only a few dollars.
One analyst expects no breakthrough on soybeans from the Trump-Xi meeting.
The WCE canola Nov26 swap rose 2.58 to 804.18 and the Matif canola Nov26 swap rose 2.85 to 862.67. India’s October palm oil imports rose about 7pc to 874,740t.
Macro: Crude fell 3.9pc even though Middle East risks are rising. Iran said a tanker caught fire after hitting a mine in the eastern Strait of Hormuz, and Iran also fired drones at US bases in Bahrain over the weekend.
Ukraine kept up its campaign against Russian refineries. It hit crude units at the Ilsky refinery, which can process 6.6Mt a year, and Zelenskyy claims more than 55pc of Russian refining capacity has been knocked out, a figure Bloomberg could not verify.
Last week’s Abu Dhabi talks ended without a breakthrough. US envoys raised the idea of Ukraine giving up the Donbas in exchange for NATO membership.
Brussels is weighing a €45bn loan to Kyiv, which still faces a €17bn funding gap for 2027.
October data showed China’s factory output slowing and consumption still weak. Beijing described Thursday’s trilateral meeting as of “groundbreaking significance”. Treasury Secretary Bessent said he still expects trade deals with Mexico and Canada, despite Trump’s threat to double tariffs on Mexico.
The Dow fell 739 points.
Several major US banks reported tech problems, and United Airlines had a system-wide outage only days after a four-hour FAA communications failure grounded flights nationwide.
The AUD is down 2.7pc for the week. Coming up are EIA inventories on Wednesday, US export sales on Thursday and Cattle on Feed on Friday.
Local: The week started firmer in the west, with canola at A$846/t, wheat at $379 and barley at $330 FIS Albany.
In the east, canola improved to $786, with wheat at $338 and barley at $280 track Geelong.
The back end of the week looks less favourable for harvest, but there should be enough time before then to get most of the canola off across Victoria and southern NSW, outside the Western Districts and other southern areas. Cereal harvest is likely to stay stop-start, which is less than ideal for those trying to fill barley boats.
Harvest is gaining momentum across SA, although cool conditions and scattered showers are still keeping growers largely to gentleman’s hours. It’s frustrating for those only just getting underway or yet to put a header in the paddock, particularly with local grower selling already putting pressure on prices.
HAVE YOUR SAY