Weather:
Argentina’s key wheat belt — Cordoba, Santa Fe, northern Buenos Aires — is running dry with below-normal temperatures through Thursday and only isolated showers forecast Friday-Saturday, crop currently sitting above 90 percent good-to-very-good.
Frost risk has resurfaced across the northern Canadian Prairies over the weekend.
Indonesia’s palm belt is cooking, with El Niño-driven dryness across Borneo and Sumatra running rainfall at a fifth of normal and farm crews being pulled off harvest and onto fire duty.
Australian spring frost risk remains the dominant forward-looking theme for local wheat — nothing fresh overnight.
Markets
Wheat got smashed across the board with the WASDE offering little relief, corn held up better on a sub-179 yield but couldn’t drag the complex higher, and beans and canola both gave back Thursday’s gains as the USDA’s soybean upgrade did the damage.
Black Sea shipping disruption escalated again with Russia hitting Odesa over the weekend, keeping export flow risk to wheat, fertiliser and coal firmly in play.
Crude dropped $2.43 despite no geopolitical reprieve, as the macro crowd flipped from Thursday’s energy-shortage narrative to Friday’s demand-destruction flag.
Malaysian palm stocks hit a 2026 high on a fifth straight monthly build, adding to the bearish tone across vegetable oils.
Day Ahead – Australia
WASDE out of the way. Nothing really earth shaking from an Aussie market perspective – yes there was a production increase but the market would be largely centred around 30 million tonnes (Mt) crop, give or take.
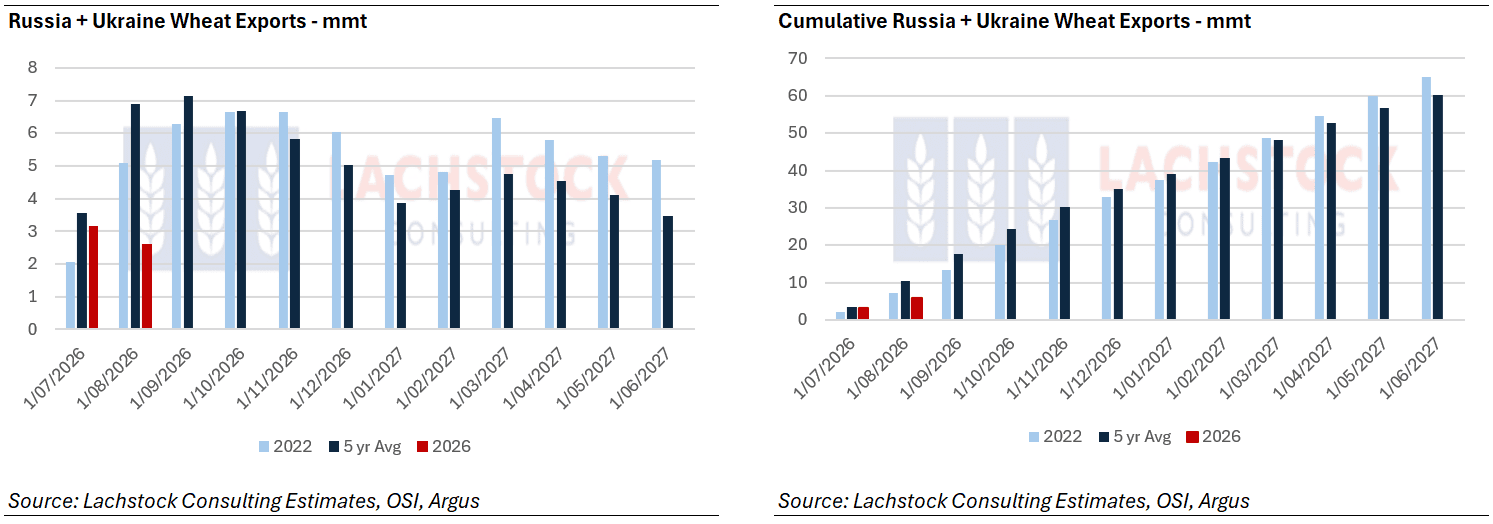
The bigger issue is the ongoing infrastructure damage in the Black Sea – fresh strikes on the weekend in Odessa. It does beg the question – 55.5Mt of exports from Russia and the Ukraine seems wildly optimistic.
The other key number for Australian wheat export prospects will be Argy production. Conditions suggest 20Mt+ even with some frost damage.
 .
Wheat: SRW Wheat 725.25, -16.00/-2.16pc day, -8.75/-1.19pc week, Kansas Wheat 798.5, -20.25/-2.47pc day, -3.75/-0.47pc week, Minni Wheat 745, -17.50/-2.30pc day, 0.00/0.00pc week, Matif Wheat 241, -4.25/-1.73pc day, -5.25/-2.13pc week, ASX Wheat 353, +0.50/+0.14pc day, -6.00/-1.67pc week.
Wheat was defensive all session.
Ags were sold off aggressively even before the WASDE landed — Thursdays macro-driven surge was a distant memory, with the same crowd screaming about the energy trade running out on Thursday waving the demand-destruction flag a day later.
The report wasn’t a must-see for domestic wheat — next spring wheat production update isn’t until the small grains summary later this month — with the all-wheat carry-out unchanged at 717 and only minor class tweaks.
The bigger mover was Australian production, lifted 3Mt to 31Mt, with world trade down slightly on reduced Russian and Ukrainian exports (down 3Mt and 1Mt respectively) offset by higher forecasts for Australia, Canada, Argentina and Kazakhstan.
Export sales of 194kt missed the 375kt expected, with the Philippines the standout buyer at 88.4kt.
Russian cash went home near US$210/t fob.
Argentina’s Rosario Board lifted its wheat outlook to 21Mt from 20.5Mt, with more than 90pc of the crop in good to very good condition, though rust has broken out in the north on hot, wet July-August weather.
Other grains/oilseeds: Corn 530.25, -3.50/-0.66pc day, -6.50/-1.21pc week, Soybeans 1296.5, -35.75/-2.68pc day, -13.25/-1.01pc week, Soybean Meal 352.8, -4.10/-1.15pc day, -2.30/-0.65pc week, Bean Oil 69.68, -2.24/-3.11pc day, +0.41/+0.59pc week, WCE Canola 817.2, -22.10/-2.63pc day, -5.30/-0.64pc week, Matif Canola 550.75, -7.00/-1.26pc day, -1.25/-0.23pc week, Palm Oil 4814, -71.00/-1.45pc day, -115.00/-2.33pc week.
Corn traded 10c+ better right after the report before fading. Yield came in at 178.5, down 2.2 from August but still above trade ideas of 178.1 — enough to keep the production-demise narrative alive, though corn couldn’t drag wheat and beans along with it today.
Smaller production took carry-out down 86 million bushels to 1.567 bilbu versus the 1.511 bilbu expected, partly offset by the USDA trimming feed and residual use by 150 milbu.
World-side numbers looked odd — EU production raised 400kt to 50.6Mt against Strategie Grains’ 46Mt, Argentine and Ukrainian export forecasts left unchanged.
Export sales of 1.928Mt beat the 1.450Mt expected, with Mexico, Japan and Colombia the main buyers, plus a 264kt daily sale to Mexico.
The market’s now all ears for harvest reports — if Black Sea corn flows are still thin a month from now the world buyer is in trouble.
In beans, yesterday’s grease-fire rally was put out before the report even began, and a benign print — yield up to 52.8, carry-out down 10 million to 310 versus 291 expected — did nothing to change the tone.
Meal fell $3.80 and bean oil dropped 222 points, though October crush firmed 3c to 227.50; export sales of 2.637Mt crushed the 1.8Mt expected.
Canola got dragged lower by the Chicago selloff and pre-weekend profit-taking, with crude’s slide adding to the bearish tone for vegetable oils broadly even as oil remained up sharply on the week — the only prop was that Prairie frost risk, with StatsCan’s first 2026-27 production estimates due September 16.
Palm added to the pile-on: Malaysian stocks climbed 7.5pc to 2.8Mt in August, a fifth straight monthly build and the highest level this year, with exports down 7pc — the inventory glut outweighing the Indonesian supply-risk story for now.
Argentine corn plantings were lifted 200,000ha, with production eyeing a record 70.5Mt on El Niño support, while the soybean planting estimate was trimmed slightly .
Macro: Crude 100.05, -2.43/-2.37pc day, +8.57/+9.37pc week, AUDUSD 0.7169, -0.00/+0.17pc day, -0.47pc week, The Dow 52573.29, +509.19/+0.98pc day, -840.96/-1.57pc week.
WTI dropped $2.43 despite no geopolitical reprieve, with the macro crowd flipping from an energy-shortage narrative Thursday to demand-destruction by Friday.
Russia hit Odesa and the surrounding region again over the weekend, with Black Sea shipping disruption to wheat, fertiliser and coal exports showing no sign of easing — the high-stakes game of chicken between end-user and exporter continues, with neither side blinking.
Xi and Modi’s met in New Delhi which added to the geopolitical noise without shifting anything fundamental for grain flows.
US equity futures were soft into the weekend on renewed AI-development jitters and hotter-than-expected inflation, keeping the Fed rate debate alive into this week’s decision.
Locally, Australia’s housing market stayed stuck in reverse — auction clearance at 58.5pc versus three-in-four a year ago — leaving the RBA boxed in ahead of Sarah Hunter’s Monday appearance and Governor Bullock fronting parliament Friday.
Local: Through the west of the country, cereal bids were stronger to end the week, with wheat at A$381/t and barley $329. Canola was steady at $882, while GM was $880 FIS Albany.
In the east, wheat was $356, barley $295 and canola $832 track Geelong.
A dry and warm week is forecast for most of the country, with the exception of WA where 15–25mm is forecast across most cropping regions. Hay is starting to hit the ground through SA, Vic and NSW, so expect some rain to appear in the forecast shortly! Hay values are around $210/t ex-farm through Vic and SA, while the Darling Downs is around $450/t delivered.
Some encouraging pulse demand out of the subcontinent, with Australian lentil business reported around US$560/t CFR Kolkata for September shipment. This looks more like short-covering than a broader shift in demand, with Canadian exports running slowly and nearby buyers turning to Australia for prompt tonnes.
Young cattle markets came under pressure this week as online listings surged 67pc to 17,500 head, with clearance falling to 78pc. Most steer and heifer categories lost 40–80c/kg, suggesting the larger yarding quickly exposed softer buyer demand despite still-solid headline value.
HAVE YOUR SAY