 Weather: Some good falls through Australia – hopefully more to come in this pattern.
The UK recorded its hottest May day on record yesterday.
The US corn belt has turned a little dry – something to keep an eye on
Temps set to return to normal in France – rainfall forecast has dropped a little.
Markets
Markets absorbed the lack of progress in Iran, well, I would probably call it an escalation dressed up as a negotiation. The fact both Iran and the US let shots fly doesn’t bode well, particularly given the sticking points which seem monumental in the scheme of things.
Todays CPI will set the tone for the direction of the RBA.
Day Ahead – Australia
Canola bounced along with energy which should continue to provide support locally. From a cereal perspective, rains and renewed interest in planting adds some incentive for the bid side to soften a little, however, there are plenty still calling for the Super El Nino and, as we all know, its all about Spring.
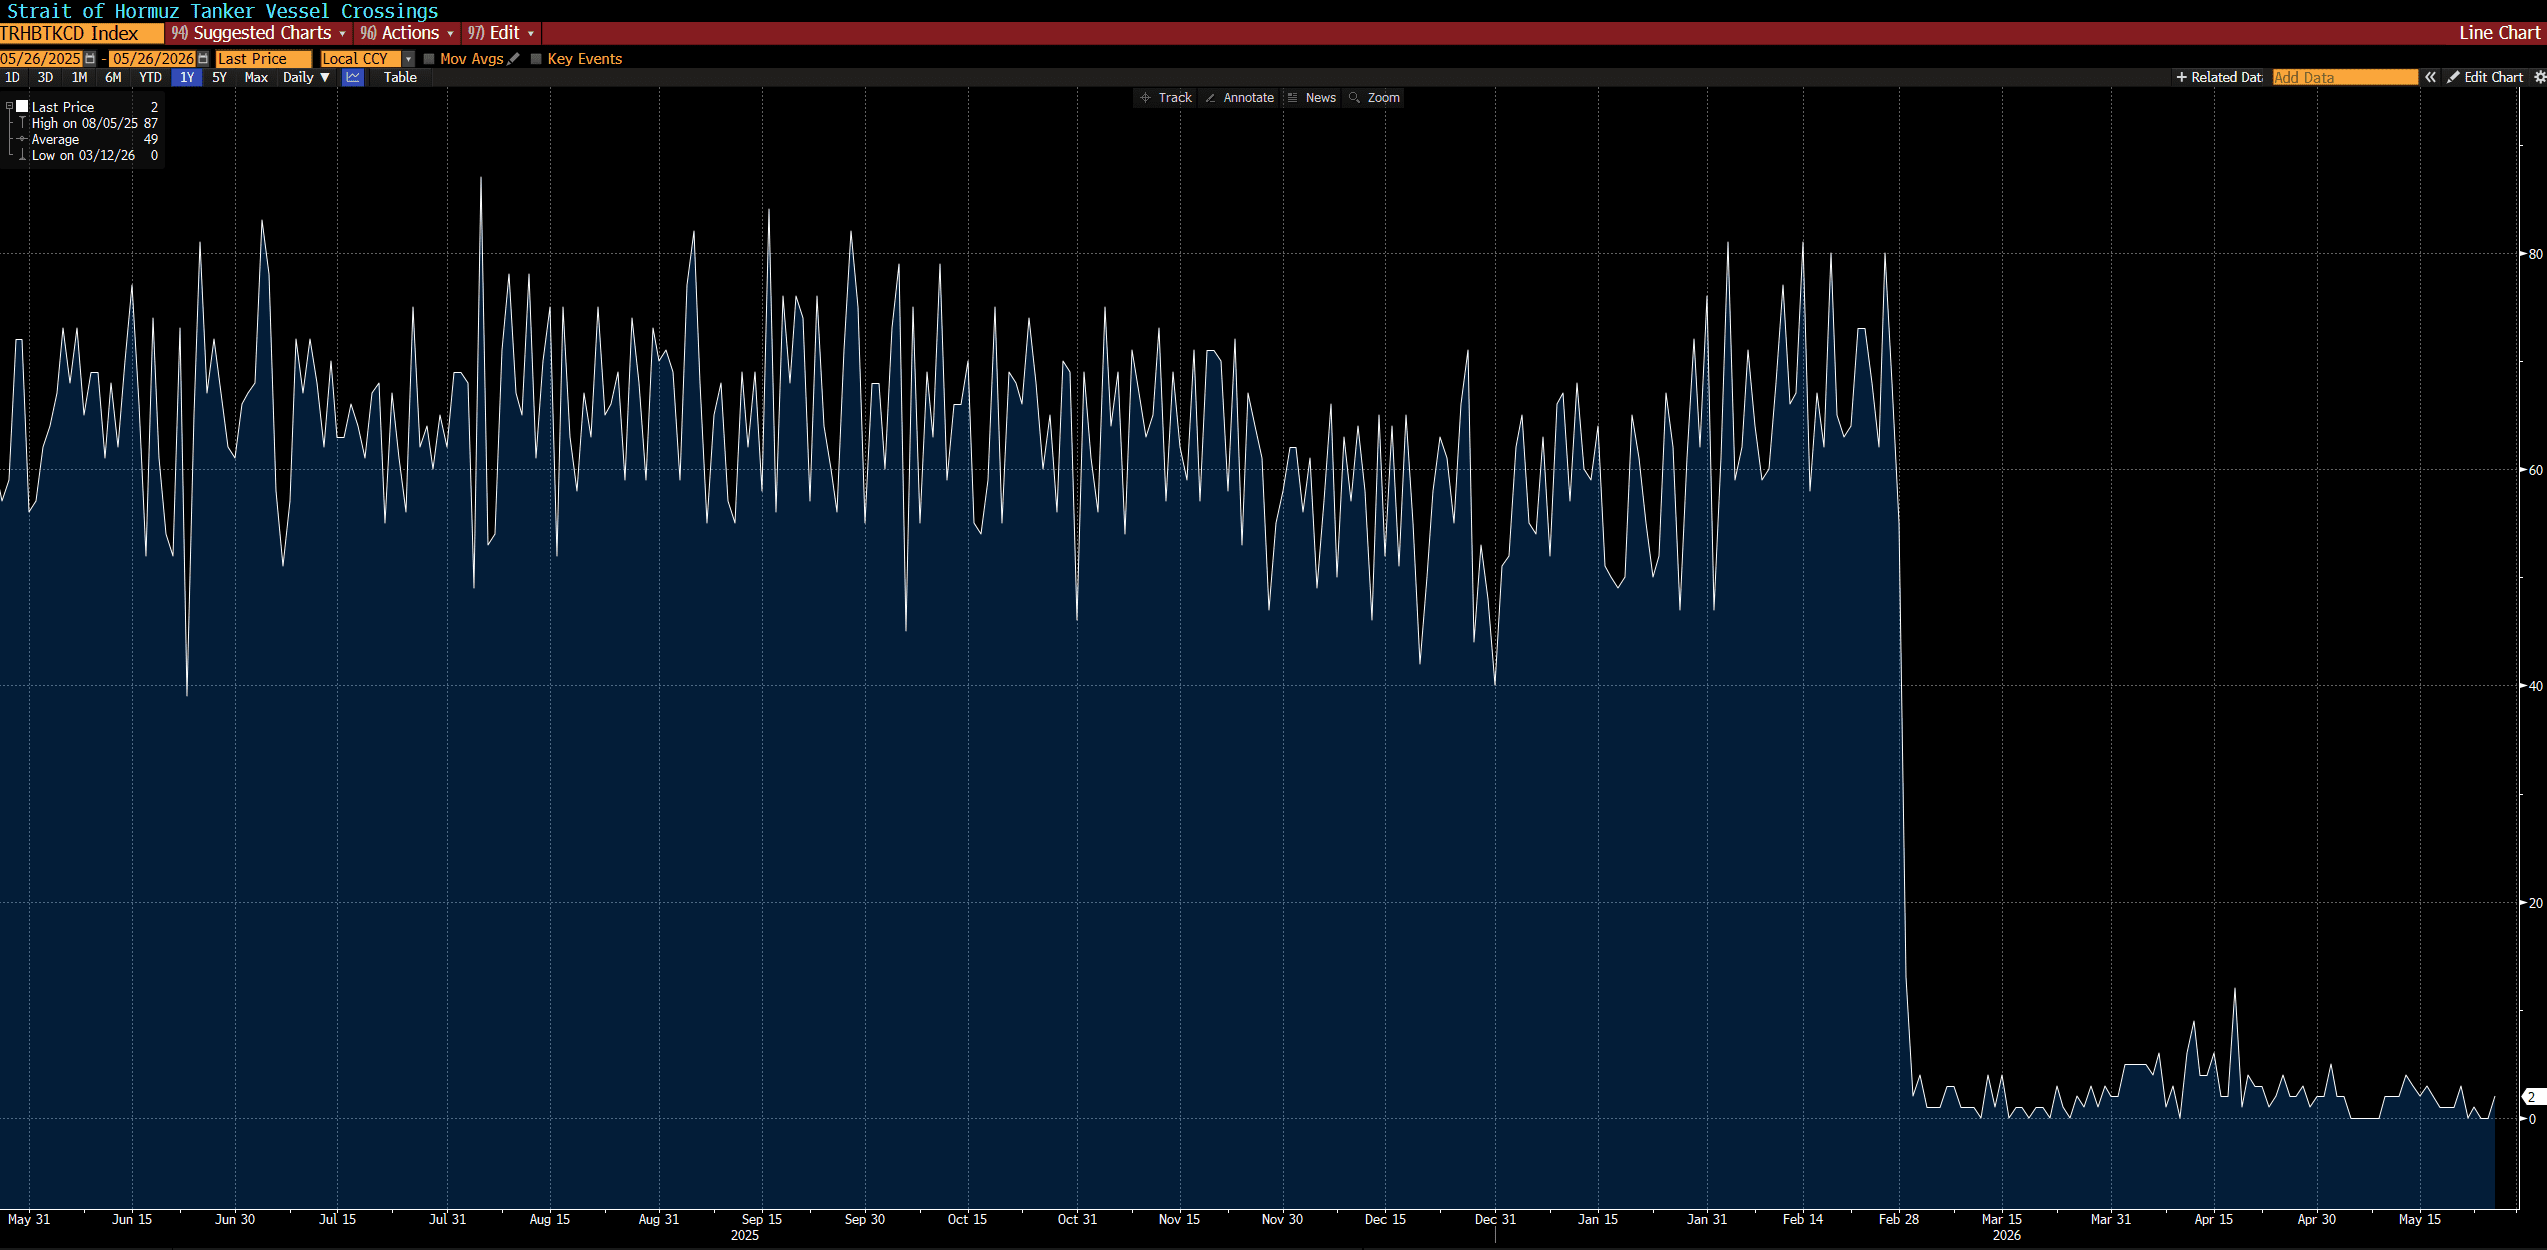
Strait of Hormuz Tanker Crossings – Source: Bloomberg
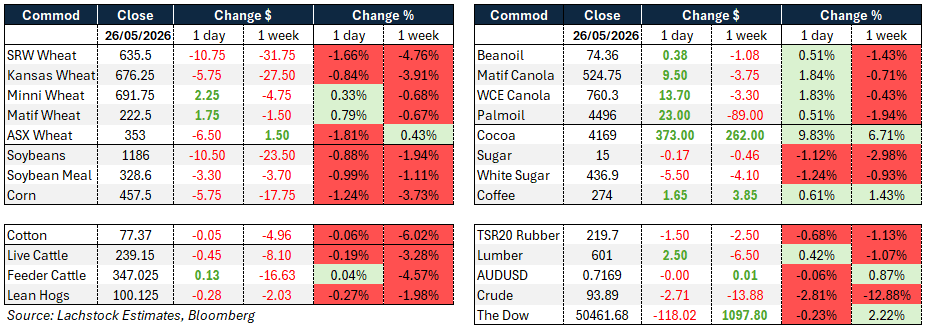
Global wheat: Chicago -10.75c, Kansas -5.75c, Matif Sep +€1.75
A mixed session with a clear north-south divide across the wheat complex. Minneapolis held the upper hand, adding 2.25c as dryness entrenched across the northwest plains, while Chicago shed 10.75c and Kansas fell 5.75c, the latter weighed by improving rainfall across key US growing areas over the long weekend.
US crop conditions came in effectively unchanged, down one point in total against market expectations for a modest improvement.
Russian cash was flat at $245 with Matif September adding €1.75.
The headline grabber remains the Rabobank Australian production estimate of 21.3 million tonnes for 2026/27, a 41% year-on-year decline driven by low prices, dry conditions and elevated input costs amplified by the Iran war. The figure sits well below the USDA’s current 30 million tonne peg and, if realised, would take Australian stocks-to-use below 15% and likely draw India back into the import market.
Recent rains have improved sentiment somewhat. On the export front, Russian seaborne shipments in April surged over 100% year-on-year to 4.9 million tonnes though May is tracking at just 3.1 million tonnes against 4.55 million in April.
Ukraine has completed 94% of spring sowing.
Fund positioning remains a drag, with sizeable long books and no fresh bullish catalyst to arrest the path of least resistance lower.
Other grains and oilseeds: Corn -5.75c, Soybeans -10.5c, ICE Canola Jul +C$14.50
Corn followed crude lower in Monday’s session, with the July contract losing 5.75c and December shedding 4.5c, before settling at $4.58 on Tuesday.
The seasonal tendency lower is asserting itself despite a broadly supportive weather narrative, with dry conditions in the corn belt expected to extend into June.
The market is treating this with measured scepticism given how frequently a dry June resolves before the critical July pollination window.
Beans were softer across the board, July losing 10.5c to settle at $11.85½, with China demand still the dominant unknown and no firm timeline on purchases materialising.
Within the complex, products diverged with meal selling off sharply while bean oil recovered on crude strength, pushing the July crush margin up 7.5c to 355.
Notably, Indian soymeal saw 25,000 tonnes of export contracts cancelled for the first time since 2021 while 80,000 tonnes of imports were booked from Africa, a sign of how far domestic prices have run.
ICE canola was the standout, erasing all of Monday’s losses with the July contract adding C$14.50 to 750.70, supported by the rally in crude, soyoil, European rapeseed and palm oil.
The July canola contract pushed back above its 20-day moving average.
Indonesian palm oil exports in March fell to 2.17 million tonnes from 2.88 million a year earlier, with several major producers now under investigation for suspected under-invoicing of exports.
Brazil is expected to lift its mandatory ethanol blend to 32% from 30% in early June.
Zambia reported a record corn harvest, up 28% to 4.94 million tonnes.
Macro: AUD 0.7171, Dow -118, Brent +2.9% to ~$100/bbl
The dominant macro theme remains the US-Iran conflict and the status of the Strait of Hormuz. Brent crude added 2.9% to approach $100 per barrel after overnight clashes near the strait, with US forces conducting what Washington described as defensive strikes on missile sites and mine-laying boats in southern Iran.
The IRGC claimed it fired on an F-35 and several drones, asserting it downed an MQ-9 Reaper. Secretary Rubio characterised negotiations as involving a lot of back and forth on specific language, suggesting a deal remains days rather than hours away.
Key sticking points include Iran’s $24 billion in frozen assets, Hormuz navigation fees, uranium stockpile disposition and the Lebanon front.
Saudi Arabia, the UAE and Qatar continue to press for a diplomatic resolution, wary of a return to the drone and missile exchanges that preceded the April truce.
Domestically, Australian CPI for April is due this morning with the market expecting 0.6% month-on-month against a prior of 1.1%, and 4.4% year-on-year against a prior of 4.6%, with trimmed mean YoY consensus at 3.4%. The result will be closely watched for RBA implications given the recent rate cut cycle .
Local markets: WA bids were softer yesterday with canola back $10 to $805 and new crop $840, wheat was $355 and $367, barley steady at $337 and $336 FIS Albany.
In the east of the country bids were back across all commodities with canola $755 and new crop $788, wheat was $335 and $359, barley $314 and $323.
Canola bids were softer yesterday on the back of futures pullback and energy sliding, with attention now on whether overnight strength in oil and futures flows through locally as Australian crop prospects continue to improve.
Some more good falls through SA, Vic and NSW over the last 24-48 hours, with falls of note including 35mm through Loxton, 30mm Donald and 120mm Dubbo.
Widespread rain across QLD, NSW and Victoria has triggered a sharp lift in direct consignment cattle grid prices, with processors now facing tight supply and some grids jumping 20c/kg this week.
HAVE YOUR SAY